
The tax code is shifting under our feet again, and keeping up is no small task. For 2025, the seven federal income tax rates themselves—10%, 12%, 22%, 24%, 32%, 35%, and 37%—are holding steady.
But don’t be fooled. The income ranges for each tax bracket have been pushed up for inflation. This simple adjustment will directly change the tax bill for millions of households.
These big beautiful bill tax changes by income bracket are the first step to smart planning, so understanding them is a priority. From our experience, these shifts in the tax code can be confusing, but you don’t have to figure it out by yourself.
This guide breaks down the new tax laws from the Big Beautiful Bill Act (sometimes called the Beautiful Bill or Trump tax plan), offering clear examples and actionable strategies to help you keep more of your money.
Our last article covered big beautiful bill tax changes by income Next, we look at big beautiful bill property taxes and what they mean for renters and owners. For the full picture, start with our main guide on the big beautiful bill salt cap.
Short Summary
- The Big Beautiful Bill Act keeps seven tax rates but shifts income thresholds upward, directly affecting every bracket.
- Lower tax brackets and an increased child tax credit bring relief to single-income households and working families.
- High earners see changes with the alternative minimum tax, mortgage interest deduction, and SALT deduction limits.
- Strategic planning using health savings accounts, capital gains strategies, and new investment credit options helps reduce liability.
- Reviewing each tax year carefully and seeking professional tax advice ensures the best use of credits and deductions.
Understanding The Big Beautiful Bill Tax Changes By Income Bracket
The big beautiful bill tax changes by income bracket adjust how households interact with the tax code in 2025. This section breaks down the main tax provisions, how the brackets have shifted, and why knowing the difference between AGI and MAGI matters.
Overview Of Core Tax Provisions
The new tax laws hold the same seven federal rates but expand the ranges they apply to. The result is that more gross income can be taxed at a lower rate. For some households, this means smaller income tax bills even without changing their income.
Redefined Brackets with Updated Thresholds
Every tax year brings changes, and this one pushed the thresholds upward. For example, a family earning $92,000 may now fall into a lower tax bracket compared to before. This effect helps them hold onto more take-home pay.
AGI Vs. MAGI In Placement
Adjusted gross income is the baseline for bracket placement, while modified adjusted gross income adds back certain items. Imagine a teacher with $70,000 in AGI and student loan interest.
Their AGI keeps them in a lower bracket, but a side gig that shifts their MAGI could bump them up.
Standard Deduction Vs. TCJA Rules
The standard deduction remains high compared to pre-2017 rules under the Tax Cuts and Jobs Act (TCJA). Under the TCJA, many shifted from itemizing to taking the standard deduction.
For instance, a couple married filing jointly may see their taxable income shrink more with today’s deduction than before the TCJA passed.
Filing Status Matters
Status still matters. Joint filers often gain more favorable thresholds. A household filing jointly can see thousands in savings compared to filing separately, even with the same total income. Households on one income should review their status.
A one-earner couple usually gains from filing jointly. An unmarried filer with a qualifying dependent may qualify for head of household.
We Help Families Close the Wealth Gap
Lower And Middle-Income Bracket Changes ($0–$100,000)
Most working families fall into this range. Here’s how lower tax brackets, credits, and deductions can shape outcomes for this income level.
Lower Tax Brackets for Working Families
Expanding the lower tax brackets means many households keep more of their paycheck. Take someone earning $55,000. They may find a few hundred dollars shaved off their tax bill just from bracket adjustments.
Expansion Of The Child Tax Credit
The child tax credit has been expanded again. An increased child tax credit is now open to more families, and the eligibility criteria reach higher incomes.
A household earning $80,000 with two children may qualify for a bigger credit than in 2024, directly lowering their tax return balance.
Standard Deduction Vs. Itemizing
The standard deduction is usually the simplest option. Still, some people benefit from itemized deductions. A single filer with high medical expenses relative to their taxable income might lower liability by itemizing.
For another person, mortgage interest and charitable gifts can tip the balance.
Key Deductions In This Range
Common tax deductions like student loan interest, IRA contributions, or certain education costs matter most here. For example, a nurse earning $48,000 who contributes to a retirement account could reduce her adjusted income enough to unlock extra tax benefits.
Credits For One-Income Households
Picture a couple living on one $50,000 paycheck with one child. As joint filers, they may owe about $1,850 before credits. A child tax credit of up to $2,200 can erase that bill. The Earned Income Tax Credit may add more, depending on income.
That money can cover rent, a mortgage payment, or a car repair. A household with no children still gains from the standard deduction and other credits.
Homeowners And Aspiring Homeowners
Owning a single-family home changes your tax picture. Mortgage interest and property taxes are itemized deductions. Many households still do better with the standard deduction.
Add up both totals before you choose. Renters saving for a home can plan ahead. Higher deduction totals may tip the balance once you buy.
Single Vs. Married Filing Jointly Example
Filing status changes everything. A single filer at $60,000 with no dependents may owe about $5,100 in tax. Compare that with a couple married filing jointly making $90,000 with two kids. Their tax credit and tax benefits can reduce the bill to less than $4,000.
Role Of Personal Exemptions And Credits
While personal exemptions remain suspended, expanded credits take their place. For retirees or families near the $30,000 mark, those credits can erase much of the liability. The final tax return often shows a smaller balance due compared to earlier years.
Upper-Income Bracket Modifications ($100,000+)
Households earning above six figures face a different set of challenges. These changes affect deductions, credits, and income reporting. Let’s walk through the key points that matter most for high earners.
Alternative Minimum Tax And QBI Deduction
The alternative minimum tax (AMT) still looms for upper-income households, but exemptions are larger. That means fewer families get caught by it.
The qualified business income deduction continues, though high earners may see limits once their income passes specific thresholds.
For example, a consultant earning $150,000 might keep the QBI deduction, but a law firm partner earning double that could lose part of it.
Mortgage, SALT, And Local Tax Limits
The mortgage interest deduction is capped, and it applies only to certain loan sizes. The SALT deduction cap rose to $40,000 for 2025, but it still limits high earners in states with heavy local tax burdens. The cap shrinks for incomes above $500,000.
Imagine a homeowner in New Jersey paying $20,000 in property tax and $25,000 in state income tax. Only $40,000 of that $45,000 can be deducted. That difference shapes final federal taxes.
Phase-Outs And Deduction Limits
Miscellaneous itemized deductions are largely phased out. High earners also face deduction phases on other benefits. For instance, large cash contributions to charity have tighter caps, while corporate charitable deductions follow stricter rules.
Tipped And Overtime Income
Workers with tips or overtime should plan carefully. The new law adds deductions for qualified tips and qualified overtime pay. The overtime deduction covers only the extra half of time-and-a-half pay. It tops out at $12,500, or $25,000 for joint filers.
The tip deduction tops out at $25,000. Both phase out at higher incomes and run through 2028. Payroll taxes still apply to this income.
Interest And Casualty Losses
High earners may deal with multiple interest payments. That includes interest paid on loans, qualified interest, car loan interest, and auto loan interest. Only certain categories remain deductible.
Personal casualty losses also have narrower rules, applying only in federally declared disaster zones.
Example Scenario
Consider joint filers earning $250,000. Their tax plan may include limits on mortgage deductions, capped SALT benefits, and partial QBI eligibility. The result is higher federal taxes compared to a family in the $90,000 range, even before credits are applied.
Visit our sister site, Keys to Prosperity, for more guides.
Strategic Planning And Implementation For 2025
The tax year is already underway, and timing matters. Smart planning helps capture credits and deductions before filing season hits. Here’s how households can prepare.
Timeline Of Changes
Most tax changes under the Big Beautiful Bill are effective for returns filed in 2026, but they apply to income earned in 2025. That means actions taken today shape next year’s outcome.
Calculating Savings With AGI And Qualifying Income
Start with adjusted gross income. Then, check qualifying income rules for credits. For example, a family with AGI of $95,000 may qualify for certain breaks. But foreign income could change that.
Key Planning Steps
Practical strategies that help:
- Use health savings accounts to reduce taxable income.
- Plan for capital gains by offsetting losses.
- Maintain a savings account for liquidity while exploring newer options like Trump savings accounts for tax-deferred growth.
- Claim every credit you qualify for, including the Earned Income Tax Credit and child tax credit.
- Keep your mortgage interest and property tax records. You need them to see if itemizing pays off.
- Ask about free tax help, since volunteer programs prepare returns at no cost for many lower-income households.
Expanded Tax Credits
Several new or expanded credits are now in play:
- Advanced manufacturing production credit
- Carbon oxide sequestration credit
- Clean electricity production credit
- Clean fuel production credit
- Investment credit
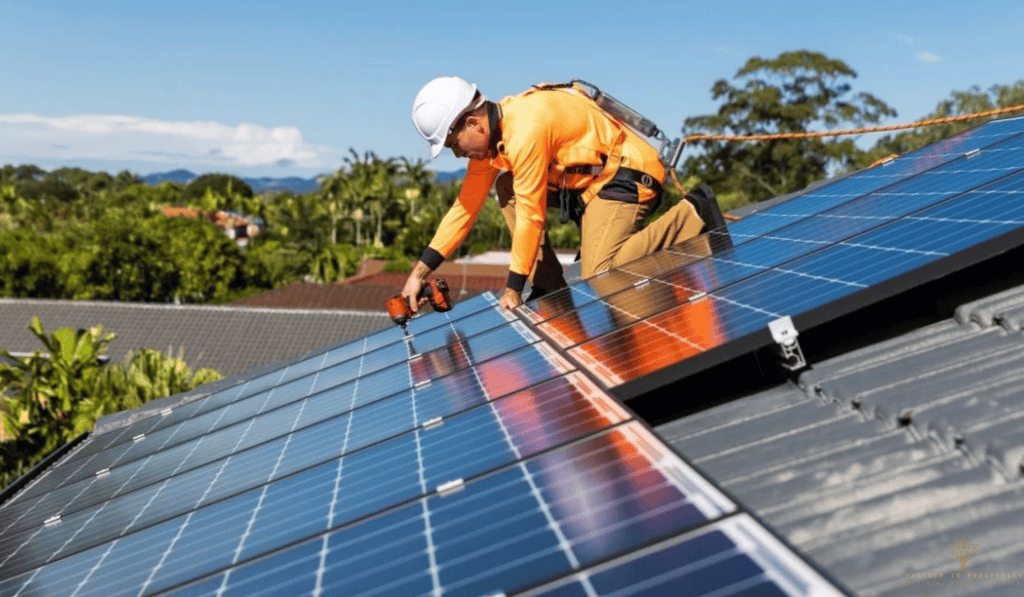
For example, a homeowner who installs solar panels could qualify for the clean electricity credit and lower taxable income.
International And Business Considerations
Multinational investors need to watch net CFC tested income rules. These determine how foreign profits are taxed at home.
Guidance From The IRS
The Internal Revenue Service updates guidance throughout the year. Checking their bulletins ensures households don’t miss updates that affect eligibility.
Vehicle-Related Deductions
Taxpayers claiming EV credits should track purchases by vehicle identification number. Without it, the credit may be denied.
Call For Professional Advice
Smart planning leads to stronger tax benefits and long-term economic growth. A qualified professional can review numbers and provide tailored tax advice before deadlines hit.
Final Thoughts
The Big Beautiful Bill Act represents a significant shift in our tax reform landscape. This new tax plan introduces many nuanced tax provisions that will affect your next tax return. Each income bracket faces a unique set of rules and opportunities.
Understand these changes, and they can help you maximize your tax benefits. We hope this guide gives you a clearer picture of what to expect for the 2025 tax year.
Tax law is complex. This is why we always recommend seeking personalized tax advice from a qualified professional. These pros can help you build a strategy tailored to your specific financial life.
Have more questions? We are here to help you navigate it all. Explore more resources and guides on our homepage to build steadier ground for your household.