
Right now, average U.S. home prices sit near $369,000, still ticking up slightly. But you know what’s even better? There are over 1.3 million homes for sale, the most choices buyers and real estate investors have had in years.
From our experience, a market shift like this means opportunity, and understanding the new Big Beautiful Bill is key to seizing it. This guide breaks down the tax cuts, deductions, and credits driving new real estate investment activity.
If you’re looking to grow your financial security, this matters to you too: the investment incentives covered here shape how much affordable rental housing gets built, how quickly distressed properties change hands, and how much capital flows into communities like yours.
For a broader look at who these provisions touch, see our guide on who benefits from the Big Beautiful Bill. The next article will give you insights on the State and local tax under the new Big Beautiful Bill.
We’ll show you how significant tax cuts, the powerful qualified business income deduction, and enhanced bonus depreciation can boost returns for real estate owners, and what that ripple effect means for renters, buyers, and families working toward housing stability.
Short Summary
- Big Beautiful Bill delivers major tax cuts via enhanced bonus depreciation and the qualified business income deduction.
- Strategic electing real property trade status can maximize pass-through savings.
- New tax credits (markets tax credits, clean energy tax incentives) and opportunity zone benefits offer layered incentives.
- Critical deadlines apply for tax years beginning after December 31, 2024.
Understanding The Big Beautiful Bill Act And Real Estate
Let’s get straight into what the Big Beautiful Bill means for property. We’ll cover its key parts, timing, and how it changes the game compared to older rules.
What The Beautiful Bill Act Encompasses For Real Estate
This isn’t just minor tweaks. The Big Beautiful Bill Act (OBBBA) fundamentally reshapes how real estate investors handle taxes.
It supercharges deductions like bonus depreciation, refines rules for pass-through entities (like LLCs and S-corps common in real estate), and introduces new tax credits. It directly impacts how you report income and recover costs across various property types.
For instance, navigating the new rules for qualified improvement property placed in service after December 31, 2024, requires careful planning we often help investors with.
These same provisions overlap heavily with rules for smaller business owners; see our breakdown of Big Beautiful Bill business benefits for that angle.
Timeline Of Implementation: It’s All About Timing
Mark your calendars! Most big beautiful bill real estate investors benefits kick in for tax years beginning after December 31, 2024. That means strategies implemented now for the 2025 fiscal year are critical.
Properties acquired or placed in service after that date fall under the new rules. Don’t wait until the last minute! Understanding this timeline is step one.
Key Differences From Previous Tax Legislation
Forget the old playbook. The Big Beautiful Bill makes significant shifts:
- Bonus Depreciation: Phasedowns from prior laws are adjusted. Knowing the new percentages for qualified property acquired is vital for cost recovery.
- Pass-Through Rules: Deductions for pass through entities see modifications, impacting how real estate owners report taxable income.
- Interest Expense: The business interest limitation rules have new nuances affecting leverage strategies. It’s a head-scratcher we see trip people up.
- Specific Property Types: Rules for agricultural real estate and certain residential construction contracts got targeted updates.
Integration With The Jobs Act And Inflation Reduction Act
Think of these laws as puzzle pieces fitting together. The Big Beautiful Bill builds upon foundations laid by the Jobs Act (TCJA) and the Inflation Reduction Act (IRA). Key integrations:
It modifies TCJA provisions like the qualified business income deduction and bonus depreciation schedules.
It expands upon IRA clean energy tax incentives, offering enhanced benefits for qualified clean energy facilities and energy storage technology within real estate projects.
For example, combining solar investments under the IRA with new OBBBA cost recovery can be powerful.
We Help Families Close the Wealth Gap
Impact On Pass-Through Entities And Real Estate Owners
This is where the rubber meets the road for many investors. If you operate through an LLC, partnership, or S-corp (pass through entities), the bill’s changes are profound:
Calculating your share of taxable income and deductions like the qualified business income deduction involves new adjusted taxable income thresholds.
Electing real property trade status becomes even more strategic for maximizing the pass-through deduction.
Rules around excess business losses are tightened, requiring careful income and loss planning, especially for active real estate developers.
Real estate owners using structures like taxable REIT subsidiaries need to review implications. We often see owners needing to reassess their entire tax strategy due to these combined changes.
Getting specific advice early pays off, for individual investors weighing these choices, our retail investor tax planning guide walks through the basics.
Qualified Business Income Deduction Benefits For Real Estate Investors
The qualified business income deduction (QBID) is a powerful tool, especially for real estate investors. Let’s break down how this 20% pass-through magic works specifically for property investments.
The QBID Explained: Your 20% Pass-Through Advantage
Simply put, the QBID lets qualifying pass-through entities (like your LLC or S-corp) deduct up to 20% of their qualified business income directly on the owner’s individual return. This isn’t a business expense deduction; it reduces your taxable income personally.
For real estate investors, this can mean thousands saved. Getting this right hinges on your business classification.
Qualifying As A Real Property Trade Or Business
Not all rental activity automatically qualifies. To tap into the QBID, your activities generally need to rise to the level of a real property trade or business. Think beyond passive rent collection.
The IRS looks for:
- Regular, continuous, and substantial involvement (like active development, management, or leasing).
- Activities beyond merely holding property for appreciation.
Meeting specific safe harbors, like 250+ hours of service per year. We often see investors qualify through active management portfolios or development projects.
Electing Real Property Trade Status: A Strategic Move
Sometimes, making such an election is smart. Electing real property trade business status locks you into using the Alternative Depreciation System (ADS) for properties, which has longer recovery periods.
Why would you do this? Primarily, it preserves your full eligibility for the QBID without phase-outs based on taxable income or wages. It’s a trade-off: slower depreciation for potentially keeping the full 20% deduction.
Analyze your specific taxable years beginning soon to decide.
Impact On Federal And Adjusted Taxable Income
The QBID calculation interacts directly with your federal taxable income. Crucially, it’s based on qualified business income after certain deductions. Your adjusted taxable income (ATI) acts as a cap.
The deduction generally can’t exceed 20% of your ATI exceeding net capital gains. High earners face phase-outs starting around $191,950 (single) or $383,900 (married filing jointly) for tax years beginning in 2025. This interplay significantly affects your final bill.
Strategic Timing Considerations
Strategic timing matters more than ever. Most big beautiful bill real estate investors benefits, including QBID nuances, apply for tax years beginning after December 31, 2024.
Plan your income streams, entity structure, and potential such an election well before your 2025 taxable year starts. Decisions made now impact deductions claimed over a year from now. Don’t leave this crucial tax strategy element to chance.
Property Classifications And Depreciation Strategies
Getting your property types and depreciation right is where the Big Beautiful Bill really shines for investors. Let’s look into the key upgrades and distinctions you need to know.
Turbocharged Bonus Depreciation Rules
The bonus depreciation game just got better. For qualified property acquired and placed in service after December 31, 2024, you can immediately deduct a significantly higher percentage of the cost upfront.
This applies strongly to tangible personal property like appliances, furniture, and equipment within rental units. In other words, shorter-lived assets. The rules for refining tangible personal property classifications are clearer now too, making it easier to identify what qualifies.
Untangling Property Type Distinctions
Knowing what bucket your asset falls into is crucial:
- Tangible Personal Property: Shorter lifespan items (5-7 years). Refers to items like carpeting, removable fixtures, specialized tools. Qualifies for full bonus depreciation.
- Nonresidential Real Property: Commercial buildings, warehouses (39-year depreciation). Different rules apply, especially for improvements.
- Residential Rental Property: Apartments, houses (27.5-year depreciation). Often has distinct cost recovery paths. Getting this classification wrong costs you money. We’ve seen investors miss out by miscategorizing such property.
Qualified Improvement Property (QIP) Wins
Qualified improvement property (QIP) finally gets consistent love. This covers interior improvements to nonresidential real property, like updating HVAC, electrical, or security systems in a strip mall.
Such property must be placed in service after December 31, 2024, to access the enhanced benefits. QIP now often qualifies for shorter recovery periods and potentially bonus depreciation, making renovations much more attractive.
Timing your project finish date matters.
Niche Advantages: Agricultural & Residential Contracts
Specific sectors get targeted perks:
- Agricultural Real Estate: Enhanced deductions for certain structures like grain bins or livestock housing placed in service in qualifying taxable years.
- Certain Residential Construction Contracts: The percentage of completion method rules see favorable tweaks for eligible contractors, improving cash flow during builds. Know if your projects qualify.
Commercial Vs. Residential Nuances
The bill treats these differently:
- Commercial Property: Focuses heavily on qualified improvement property benefits and nonresidential real property cost recovery tweaks.
- Residential Property: Often emphasizes deductions related to residential construction contracts and specific tenant improvement allowances. Your tax strategy should reflect your primary focus.
Clean Energy & Storage Investments
Building on the Inflation Reduction Act, the Big Beautiful Bill adds sweeteners:
- Qualified Clean Energy Facilities: Enhanced deductions for solar, wind, or geothermal systems placed in service.
- Energy Storage Technology: New, favorable rules for battery storage installations within real estate projects. Significant cost recovery acceleration is possible here. To qualify, projects must begin construction within specified windows.
Navigating Business Interest Limits
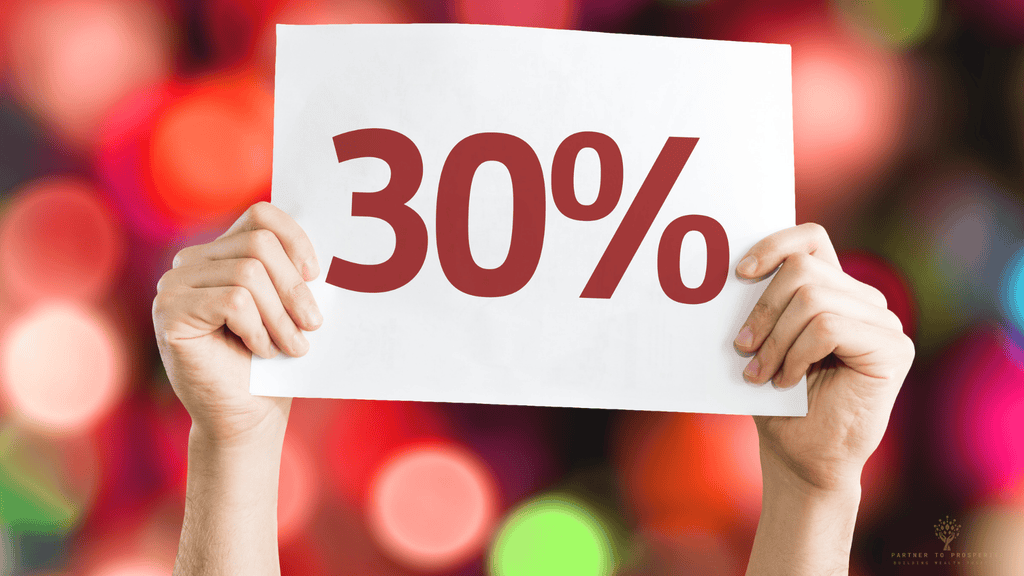
The business interest limitation rules (Section 163(j)) got refinements. Generally, your interest expense deduction is capped at 30% of adjusted taxable income. Smart moves include:
- Electing real property trade status (which exempts you from this limit).
- Carefully structuring loans secured by real estate.
Timing large debt acquisitions around taxable years beginning to optimize interest deductions. This often requires crunching numbers early.
Managing Excess Business Losses
Rules around excess business losses tightened slightly. You can generally only offset $289,000 ($578,000 MFJ) of non-business income annually with real estate losses.
Key strategies involve:
- Utilizing the business exception available to certain active participants.
- Structuring income streams across entities to stay under thresholds.
Converting suspended losses into future deductions. And as you know, planning prevents surprises at tax time.
State & Local Tax (SALT) Coordination
Don’t forget state and local taxes. While the federal big beautiful bill real estate investors’ benefits are substantial, local tax rules vary:
- Some states conform to federal tax cuts and deductions like bonus depreciation automatically.
- Others, especially high tax jurisdictions, decouple or add complexity. Pay taxes strategically by understanding your state’s stance. Coordination prevents double trouble.
Smart Financing & Fair Market Value
Financing costs matter more than many realize:
- Interest Capitalization Provisions: Know when interest expense during construction must be added to the property’s basis instead of deducted immediately.
- Fair Market Value Assessments: Lenders often require these for loans secured by property. Ensure appraisals reflect true fair market value to support loan terms and potential deductions.
- Bond Financing Threshold: Projects using certain tax-exempt bonds have specific rules. Understanding these thresholds affects your financing cost structure. Getting this right impacts your bottom line significantly.
Final Thoughts
Navigating the Big Beautiful Bill unlocks serious savings for savvy real estate investors, and those savings ripple outward into the housing market families depend on.
These 2025 changes offer tangible tax cuts and smarter cost recovery paths for investors, while credits like LIHTC and NMTC work to expand affordable housing supply where it’s needed most.
Got specific questions about how these changes affect you? Explore our resources and support tools on our homepage today. Your next step toward financial stability starts there.